Reverse Mortgages Aren’t Under-Sold. They’re Under-Explained.
September 22, 2026
Blanc Labs
Abstract: Households led by Canadians over 65 hold about $2.2 trillion in housing equity. Reverse mortgages account for half a cent on every dollar of it, and only about one per cent of Canadians over 55 have one. Reverse mortgage lenders are working on price, on product and on capital, and all three matter. The problem nobody in the market can fix on their own is simpler and harder: most of the people who would benefit cannot say what the product is, and reassurance about an irreversible decision cannot come from the party that profits from it. That makes explanation a public good.
The wall every market hits
An industry survey this year found that 15 per cent of Canadians over 55 would consider a reverse mortgage, but only one per cent have one. I have come to think of that gap as the market, and it sits on a large base: Canada has 8.1 million people over 65, three-quarters of the households they lead own their home, four in five of those homes are paid off, and a third of our seniors receive the Guaranteed Income Supplement. The reverse mortgage was designed for exactly this population, and the book of Canadian reverse mortgages has grown about 18 per cent a year since 2019. Even so, it amounts to half a cent for every dollar of the housing equity those households hold.
What surprised me when I went looking is that no country has closed the gap. In the United States, where the government insures the loan and every borrower sits through independent counselling first, between one and two per cent of eligible homeowners hold one. In South Korea, where the state guarantees the payments, nine in ten older homeowners know the product exists, one in five say they would sign up, and two in a hundred have. Britain has done best of all, with regulated advice, an industry guarantee that nobody can owe more than their home is worth, and a decade of cheap money: about four per cent of over-55s who own their home outright. Then rates rose in 2023, and British lending fell by more than half.
The wall is not made of safety, and it is not made of awareness. Canada, with none of that architecture, has about one per cent of its over-55s in the product and is growing faster than any of these markets. The Canadian reverse mortgage, on its current path, could reach only two per cent of the total addressable market (TAM). What interests me is that none of these markets got where they are by explaining the product to the people who never ask. Korea had a state guarantee and Britain had cheap money. Explanation at scale is the one lever nobody has pulled, and I think it is the one that could carry Canada past the point where everyone else stalled.
The trust paradox: who can a homeowner believe?
A 2017 academic survey of 2,140 homeowners aged 55 to 75 found that 77 per cent had heard of reverse mortgages and 45 per cent could correctly identify one. A survey commissioned by a lender this spring found that, among homeowners over 45 who had heard of the product, 53 per cent believed the lender takes ownership of the home. The federal consumer regulator’s own guidance says the homeowner keeps it. In other words, half the people who have heard of this product believe something about it that is simply not true.
I do not read this as distrust of banks. Older Canadians turn to their bank for financial advice more than almost anyone else. It is that the decision is irreversible, and where the barriers have been measured, the biggest one is fear of a decision you might regret, well ahead of cost, inflexibility or inheritance. What moves that fear is reassurance. Hence the paradox: the lenders have the knowledge and the money to provide it, but the reader knows who paid for the ad. In a product where the most common concern among Americans who know it is being scammed, that is fatal. A homeowner in a U.S. regulator’s focus group put it better than I can: “I feel more comfortable if the government is behind it. Otherwise it is just business.” Every dollar the industry spends reassuring people about reverse mortgages is discounted at the source. The people best placed to make this product feel safe are the people whose reassurance counts for least.
That is what makes explanation a public good in this category: valuable to every lender, and supplied credibly only by someone independent of them. And explanation does move people. In a Korean experiment, a single sentence correcting a belief about inheritance raised intention to enrol by seven points, more than either of the structural reforms tested beside it. Most Americans who reach an independent counsellor take the loan; the loss happens earlier, among people who never call because they think they already know the answer. Explaining will not make them all borrowers. It will let them decide.
Growing the pool: what could lenders do together?
Every lender in this category spends to win the borrowers who already know to ask: rate cuts, broker commissions, advertising. Very little of it reaches the fourteen in fifteen who would consider the product and do not have it.
For three decades one lender was the market, and its advertising built whatever awareness the category has. When a second lender arrived, it grew on that awareness, and the category has grown faster than the first lender since. That is spillover, and it is the reason joint efforts usually fall apart: whoever pays, everyone benefits. In reverse lending, though, the free-rider problem is unusually small, because two lenders hold more than nine-tenths of the market between them. Whatever they spend growing the pool, they keep nine-tenths of the result.
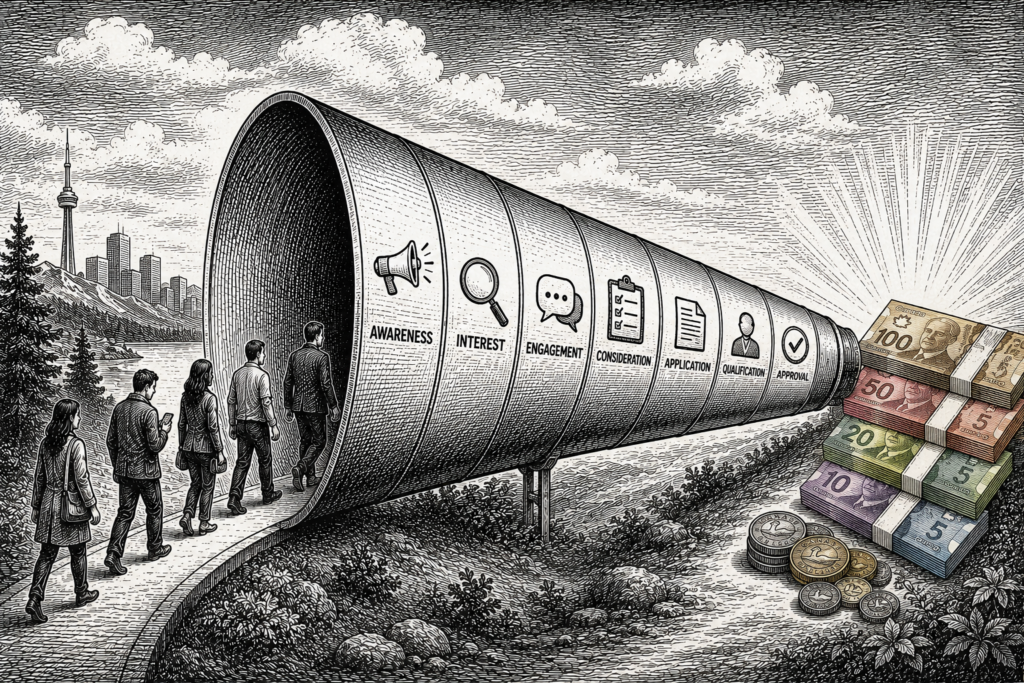
The harder question is what to spend it on. More awareness helps, and advertising is good at buying it. What closes the gap between knowing about a product and deciding on it is a guided conversation. In the cleanest experiment I have found, information alone nearly doubled enrolment in a benefit program, and information plus a person to walk through it tripled it. For this product, that means a patient, unhurried conversation with the person’s own numbers in front of them, from a party with no share to defend, before they have decided to talk to any lender. Until recently that meant a patient human expert for every household, which no lender could afford at scale. Specialist conversational AI that works from the person’s own numbers, guides and helps but does not sell anything, can now hold that conversation with every one of the fourteen in fifteen. That is new, and it changes the arithmetic for the whole category.
Reverse mortgages in Canada are at one per cent, and the markets that did best stalled at two to four. Lenders can keep bidding for the few who already know to ask, or reach the fourteen in fifteen who would consider one and never ask. The second is the only growth strategy this category has ever had, and nobody has run it yet.
Five key points
- Fifteen per cent of Canadians over 55 would consider a reverse mortgage; only one per cent have one. That gap is the market.
- The markets that did best stalled at two to four per cent, even with state guarantees, regulated advice and 90 per cent awareness. The ceiling is neither safety nor awareness, and nobody has tried personalized explanations at scale.
- Half of Canadians who have heard of the product believe something false about it, and reassurance cannot come from the party that profits from the decision.
- Two lenders hold more than nine-tenths of the market and would keep nine-tenths of any growth they fund, so the free-rider problem that stops most efforts barely exists here.
- For any product line, ask whether growth is limited by demand or by comprehension. Where it is comprehension, personalized explanation grows the pool, and a guided conversation is now affordable at scale.
Sign up for the CLA Finance Summit Series
Hamid Akbari is the founder and CEO of Blanc Labs, which builds AI agents for lenders. He spent ten years building digital and AI products inside regulated financial institutions.