From Detection to Prevention: Rethinking Fraud Intelligence in Lending
September 16, 2026
From Detection to Prevention: Rethinking Fraud Intelligence in Lending
Abstract: Fraud is no longer a back-office problem for Canadian lenders. It is a balance sheet risk that increasingly moves across institutions faster than the intelligence needed to stop it. Although lenders are investing heavily in AI and more sophisticated detection tools, those tools remain constrained by fragmented data and limited information sharing. Closing the gap will require lenders, credit bureaus, insurers, dealers, technology providers, and law enforcement to build secure, privacy-preserving systems that allow fraud signals to travel before funds are advanced. The industry’s next advantage will come not from detecting fraud more accurately after the fact, but from connecting intelligence early enough to prevent it.
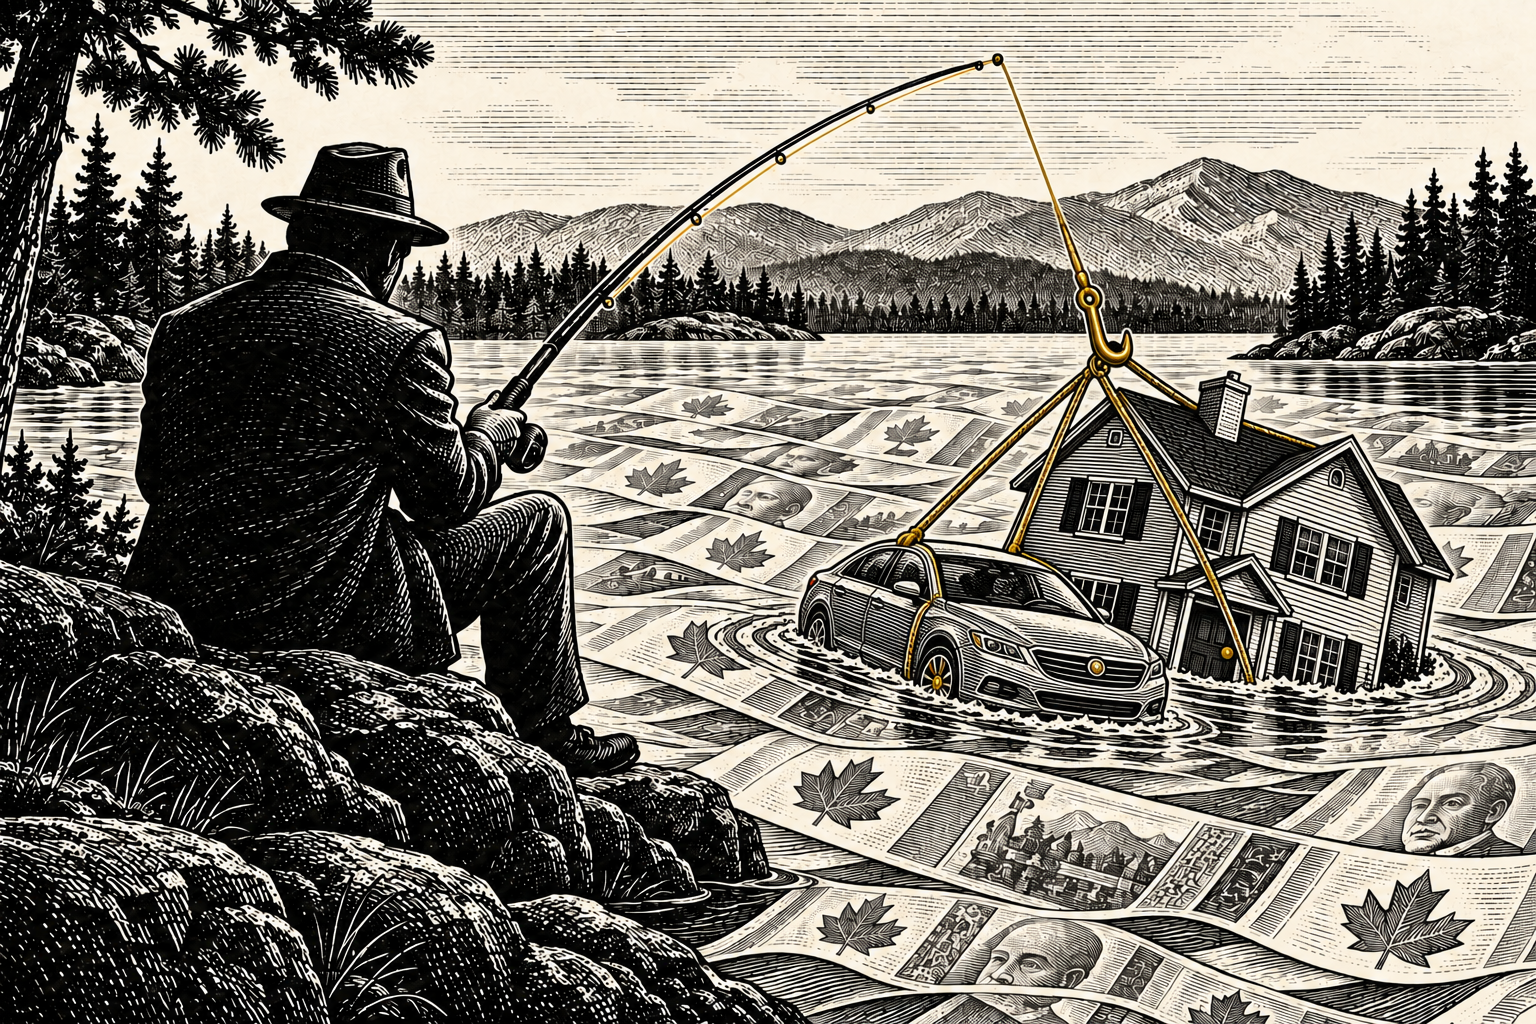
Canadian lenders are getting better at catching fraud. They are not getting any better at stopping it before the money is gone, and that distinction is now the single most expensive gap in the industry. TransUnion’s H2 2025 survey of Canadian business leaders put the cost of fraud to Canadian businesses at an estimated C$111 billion over the past year, up 42% from the year before. The tools exist to close that gap. What is missing is the connective tissue between the lenders, credit bureaus, insurers, dealers, technology providers, and law enforcement agencies that each hold a piece of the picture but rarely share it in time for it to matter.
Section One: Fraud has stopped being a back-office problem
Fraud in Canadian lending is no longer a niche operational risk handled quietly by a compliance team. It is now a balance sheet issue, and the numbers back that up. TransUnion’s H2 2025 survey found that fraud costs Canadian businesses the equivalent of 7.2% of annual revenue, with synthetic identity fraud, the blending of real and fabricated personal information, accounting for more than a quarter of total losses. Equifax Canada’s most recent data shows that first-party fraud, in which applicants misrepresent their own income or financial position, rose 31% nationally year over year between the final quarters of 2024 and 2025, driven largely by sharp increases in the credit card and banking sectors.
Auto lending fraud actually moved in the opposite direction over the same period, falling 19.4%, though Equifax cautions that potential losses tied to suspected fraud within delinquent auto portfolios remain significant. The broader shift toward identity-based fraud has been building for some time: an earlier Equifax survey found that identity fraud accounted for roughly three-quarters of all fraudulent applications across sectors by late 2023, up from about two-thirds the year before.
What makes this moment different is not just the scale of the losses. It is the shift in who is committing fraud and how. Economic pressure is pushing more borrowers toward first-party misrepresentation rather than classic third-party identity theft, and that shift matters because the two require entirely different detection approaches. A static document check can catch a stolen identity. It struggles to catch a real person quietly inflating their own income. Catching that requires context: How does this application compare with patterns across other lenders, product types, and regions? That context does not live inside any single institution’s systems. It lives across the ecosystem, in pieces, mostly unconnected.
Section Two: Detection after the fact is a design problem, not a technology problem
The instinct across the industry has been to respond with better detection tools, and that investment has been real. KPMG’s research on Canadian companies found that 67% plan to increase fraud prevention and detection budgets in 2026, with much of that investment aimed at shifting away from point-in-time checks toward continuous, risk-based controls layered across identity, behaviour, devices, and channels. Gartner’s most recent finance AI adoption survey found that 59% of finance leaders now use AI in their operations, essentially flat from 58% in 2024, following a sharp jump from just 37% in 2023. Gartner itself describes this as a levelling-off period rather than continued acceleration, even as adoption remains at a historic high.
None of that investment is wasted, but it is solving only half the problem. Better models sitting on top of fragmented, siloed data still mean that each institution is essentially fighting fraud with a partial map.
The IMF made this point directly in an April 2026 technical note, warning that fragmented data architectures are the primary obstacle weakening the fight against fraud and that AI tools perform far more effectively in integrated systems built on shared data than in the siloed environments most institutions still operate in today. That is the core issue. Most of the industry’s fraud infrastructure is built to explain what has already happened rather than to prevent it from happening in the first place.
The fix is not another point solution. It is connectivity. A lender, a credit bureau, an insurer, a dealer network, and a technology provider each see a different slice of a borrower’s behaviour, and right now those slices rarely meet before a loan is funded. McKinsey’s banking research, published in 2023 and still commonly referenced today, puts the potential value of generative AI and advanced analytics at between $200 billion and $340 billion annually across global banking through productivity gains alone, a figure that grows substantially once risk reduction is factored in. That value is realistic only if the underlying data those models draw on becomes less fragmented, not just faster to process.
Section Three: What this means for lenders and what should happen next
For CLA members, the implication is direct. The lenders best positioned over the next few years will not simply be the ones with the sharpest fraud models. They will be the ones that have built, or plugged into, the connective infrastructure that lets fraud signals travel between institutions before a loan is disbursed rather than after a loss is booked. That includes structured data-sharing arrangements with credit bureaus and insurers, tighter feedback loops with dealer networks on application-level red flags, and a genuine willingness to treat fraud intelligence as an industry-wide asset rather than a competitive one.
This is not a call for lenders to expose sensitive customer data indiscriminately. Privacy-preserving approaches to shared intelligence, including techniques that allow institutions to match suspicious patterns without exposing underlying personal data, are maturing quickly and deserve serious attention from Canadian lenders and their regulators. The question worth asking at every institution is not whether to participate in broader fraud intelligence sharing, but how quickly and on what terms.
Canada’s lending industry does not have a fraud detection problem. It has a fraud intelligence problem, and those are not the same thing. Detection tools are more sophisticated than ever. What is missing is the plumbing that lets those tools see the full picture before a decision is made, not after a loss is written off. The lenders, bureaus, insurers, and technology providers that solve that connectivity problem first will not just reduce losses. They will originate with more confidence, price risk more accurately, and build the kind of trust with regulators and customers that comes from getting ahead of a problem instead of cleaning up after it.
Five key takeaways
- Fraud has moved from a compliance issue to a balance sheet issue, costing Canadian businesses an estimated C$111 billion in the past year, a 42% increase year over year.
- The nature of fraud is shifting toward first-party misrepresentation, which is harder to catch with static checks and requires cross-institutional context to detect reliably.
- AI adoption in fraud detection has reached a historic high, but models built on fragmented, siloed data can solve only part of the problem.
- The real gap is not technology. It is the missing connective infrastructure between lenders, credit bureaus, insurers, dealers, and technology providers.
- The lenders that move first on structured, privacy-preserving fraud intelligence sharing will be positioned to originate with more confidence and incur lower losses than those still working in isolation.
Sign up for the CLA Finance Summit Series
 Event Insights